Nine carriers answered. Now build the comparison.
Nine quotes, nine layouts, three weeks. blankit sends the RFQs, reads what comes back and lines it up against the plan you asked for — so you get the evening back.
A prospect
A group you do not yet administer is its own record. Market it on demographics and a target design; when it signs, it converts to a client with its quote history attached.
A client you already administer
The booklet on file becomes the design carriers are asked to match, and the claims and premium history goes with it.
On its own, or alongside a renewal
Run a full remarket by itself, or test a renewal against the market. When both run at once, the client gets both documents.
Quoting two designs is two markets — never one with more columns.
A cheaper carrier, not a smaller plan
Every comparative figure is drawn inside a single design. A difference on the grid is a difference between insurers, not between plans.
Every difference is highlighted
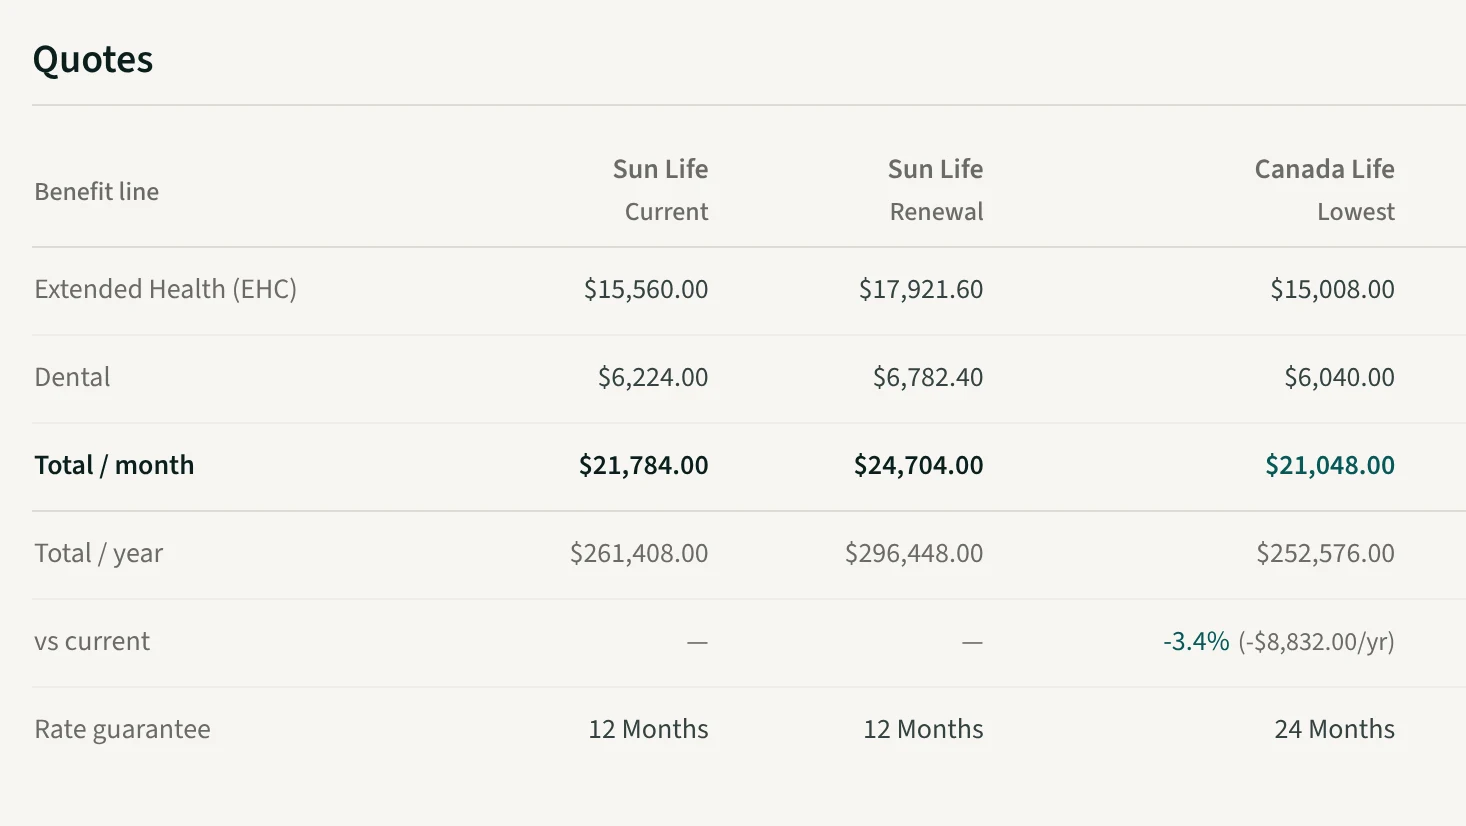
The group's current plan, read from their booklet, sits beside the quotes. Any coverage that differs from it, or from most of the other quotes, is highlighted — and two carriers saying the same thing in different words are not. Any figure read from a quote can be corrected where you see it.
One branded RFQ per carrier.
Import the census from blankit’s template or whatever the employer sent — an HR export, a payroll extract. Every row comes back, with the ones that need attention flagged.
Each carrier gets one RFQ package in your firm’s branding: the design line by line, the census, any claims history, the current carrier’s renewal to beat, the underwriting answers every carrier asks for, and the client’s own booklet. A missing or oversized booklet never holds the RFQ back.
The covering email is read too
Rate guarantees, target loss ratios and conditions often live in the email, not the PDF. Both are read, and the quote wins where they disagree.
Rates, not the carrier’s premium
The unit rate is stored, not a premium struck against the carrier’s own assumed census. What the incumbent charges today and asks for renewal stay separate.
Every carrier on the record
Every insurer that answered is listed with its caps and guarantees, and every decline with its reason. The detailed grid shows the finalists.
A marketing report from the client’s last broker reads too, one carrier column at a time.
Drop every carrier’s files
Drop every carrier’s files at once — on the case, or on the Marketing list to have each one filed on its case. Every file shows as it is read, and files that are one carrier’s quote sent in parts are read together.
Compare every benefit
Then the comparison: every benefit, class and tier priced side by side; a check that every carrier priced the same head count, read from each carrier’s own quote; each employee’s premium under every carrier; and saved checkpoints that show what each quote has moved since the last round.
Flex plans and forecasts
Marketing a flex plan? Set the credits, the election deadline and which designs employees choose between, at the carrier’s rates or the employer’s own prices, and see what each option costs per tier from every carrier that quoted.
For your eyes only: a premium forecast puts staying with the incumbent beside every quote for up to ten years, through each carrier’s rate guarantee and caps, on increases you can adjust. Each quote is tested against the carrier’s own target loss ratio on the group’s trended claims, and every RFQ asks carriers to state any marketing investment in the rate — so you can see what a price is likely to return to.
The Benefits Presentation, in your branding.
Your firm’s name, logo and colours — as a PDF, or an editable version if you want to rework the narrative first. Both come from the same view of the market, so they cannot disagree.
It opens with a contents page that links to every section, then an executive summary: who you approached and how they answered, and for each plan design what the group pays today, the lowest quote and the difference. The Marketing summary follows, with every quote that came back and what it was priced on, and which carriers declined, with the reason they gave.
A Claims Outlook answers the sponsor’s real question: how long does this price hold? It projects the group’s own health and dental claims against the quoted premium over three to five years.
Winning the case is where the move starts.
A checklist dated from the start
Marking a quote sold opens a task for every step of the move: the broker-of-record letter, notice to the current carrier, no-loss no-gain, members on claim, the spending account, enrolment, payroll and the first bill. Each one is due a set number of days before or after the effective date.
The client switches on the day
Until the new coverage starts the old carrier still insures the group, so the client stays with them. On the effective date blankit switches the client and stops the old booklet answering employees.
Steps that close themselves
Filing the new carrier’s booklet, the old carrier’s clawback reconciling on a commission statement, and the new carrier’s first bill matching the rates you sold each tick their step without anyone remembering to. Upload the first bill or forward it, and blankit checks it before the sponsor pays.
Each move has its own page on the client, moving from Sold through Notices sent, Enrolled and New carrier live to Run-off closed, with a Moving to a New Insurer guide made out for the client, their carriers and the dates.
Get the evening back.
Bring a market you have already worked, and we will rebuild it in front of you.